
 1 day ago
3
PROTECT YOURSELF with Orgo-Life® QUANTUM TECHNOLOGY
Orgo-Life the new way to the future Advertising by Adpathway
Article content
Q. I am a recently divorced 48-year-old woman with one son, aged 10. I earn $145,000 annually and was given the house — my principal residence — in the divorce settlement, which is a fully paid off three-bedroom townhouse in Montreal. My ex-husband also pays $550 monthly in child support that ends when my son reaches age 18. I have no other savings or investments except for a $20,000 emergency fund. I can likely save $3,000 monthly after all expenses and was wondering how I should save and invest this money. Retirement savings and education savings for my son are key priorities for me. —Stefania B. in Montreal
THIS CONTENT IS RESERVED FOR SUBSCRIBERS ONLY
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman, and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
SUBSCRIBE TO UNLOCK MORE ARTICLES
Subscribe now to read the latest news in your city and across Canada.
- Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman and others.
- Daily content from Financial Times, the world's leading global business publication.
- Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account.
- National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on.
- Daily puzzles, including the New York Times Crossword.
REGISTER / SIGN IN TO UNLOCK MORE ARTICLES
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account.
- Share your thoughts and join the conversation in the comments.
- Enjoy additional articles per month.
- Get email updates from your favourite authors.
THIS ARTICLE IS FREE TO READ REGISTER TO UNLOCK.
Create an account or sign in to continue with your reading experience.
- Access articles from across Canada with one account
- Share your thoughts and join the conversation in the comments
- Enjoy additional articles per month
- Get email updates from your favourite authors
Sign In or Create an Account
or
Article content
Advertisement 1
Article content
Answer: Hi Stefania. My suggestion for your son’s education is to contribute $5,000 a year to a registered education savings plan (RESP) so you maximize the grant. The annual contribution to get the maximum grant is $2,500. However, you can go back one year at a time to pick up missed grants and the grant stops becoming available once your son turns 17. You are likely going to help your son with his schooling, so why not contribute to the RESP and get the government grant?
Article content
Article content
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
Article content
It’s not as clear-cut an answer when it comes to saving for retirement. The standard strategy is to maximize your registered retirement savings plan (RRSP) first, then your tax-free savings account (TFSA), followed by non-registered investments. That is the best or the worst advice you can follow. It’s all dependent on how you manage your money.
Article content
I will show you the textbook approach, as well as how people more commonly behave, then you can decide which is right for you.
Article content
To set this up I assumed inflation at two per cent and investment returns of five per cent, made up of a combination of interest, dividends and capital gains. Your living expenses are about $71,000 annually, after tax and investment contributions. I also assumed you will want the same $71,000-a-year after-tax income in retirement, which would start in January of the year you turn 65. Canada Pension Plan (CPP) and Old Age Security (OAS) payments start at age 65 as well.
Article content
Advertisement 2
Article content
I calculated the results of investing $30,000 a year, plus any tax savings, other year-end savings after spending $71,000 a year after tax, plus the $5,000 once you stop adding to the RESP. This illustrates the impact of investing the RRSP tax refund. I looked at what happens if the money is invested into one of three scenarios: 1. all of it goes into a non-registered account; 2. the TFSA maximum plus the remaining amount to a non-registered account and 3. $30,000 to an RRSP and the surplus to a TFSA and then to a non-registered account.
Article content
Article content
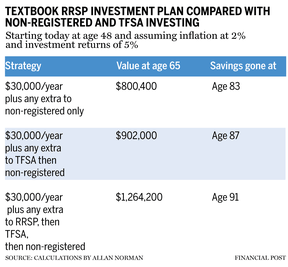
This is an example of the textbook RRSP strategy working. The calculations indicate that under scenario 1, putting your money into a non-registered account, your savings at age 65 are $800,400 and savings are spent by age 83. With scenario 2, contributing to a TFSA first, you will have $902,000 at age 65 and you will spend it all by age 87. With scenario 3, contributing to an RRSP first, you will have $1,264,200 by age 65 and it will be spent by age 91.
Article content
Article content
The RRSP results in this scenario are, I feel, representative of what most planners and writers present.









 English (US) ·
 French (CA) ·
 French (FR) ·