
 10 hours ago
2
PROTECT YOURSELF with Orgo-Life® QUANTUM TECHNOLOGY
Orgo-Life the new way to the future Advertising by Adpathway
VENEZUELA · BANKING
Key Facts
- —The country Venezuela is an oil-rich South American economy whose banking system lends far less than those of its neighbours.
- —Why it matters Companies, importers and investors that want to work in Venezuela find that local banks lend very little, which limits financing for local partners.
- —Why now Ecoanalítica, a Caracas economic consultancy, drew attention to the comparison on Saturday 17 October 2026, days after the national business federation raised the same complaint.
- —What happened Bank lending stands at only 3.4% of GDP, against 75.3% in Chile, 69.5% in Panama and 46.1% in Colombia.
- —The numbers Banks must park about 73% of deposits at the central bank, and the surcharge for missing that reserve rose from 48.8% to 144%.
- —What it means for you US firms and exporters should expect little local bank financing for Venezuelan partners and customers.
- —Still open Whether the central bank eases the reserve rule or lets banks lend against dollar deposits.
- —Power Index Venezuela ranks 13th of 14 in The Rio Times Latin America Power Index, with 27.0 points (October 2026 edition).
Venezuela bank credit is only 3.4% of the country’s GDP, the economic consultancy Ecoanalítica said, as reported on Saturday 17 October 2026. That is a fraction of the level in Chile (75.3%), Panama (69.5%) and Colombia (46.1%).
For US readers, this matters because companies and investors weighing Venezuela will find almost no local lending to work with. Local partners may therefore have to fund orders and projects from their own resources.
The warning follows the national business federation Fedecámaras, which raised the same gap at its 82nd annual assembly, as reported on Tuesday 13 October. Our earlier guide Who Runs Venezuela’s Economy, the Key Players in 2026 explains who sets the rules.
What Ecoanalítica Said About Venezuela Bank Credit
Ecoanalítica is a private economic research firm based in Caracas. It posted the comparison on its Instagram account, and the outlets Descifrado and La Patilla reported it on Saturday 17 October.
The firm put Venezuela bank credit, meaning the loan portfolio of the banks, at 3.4% of GDP and called it a significant lag behind the rest of Latin America. It listed Chile at 75.3%, Panama at 69.5% and Colombia at 46.1% as comparison points.
The posts do not say which year of GDP the firm used or whether the figure covers gross or net loans. Ecoanalítica has not, in the coverage reviewed, published a full methodology note.
The firm also described the gap as room to grow. In its view the banking sector has potential to expand once the rules that hold lending back are changed.
Follow this story
Get an email when there’s news on venezuela economy
Free. One email a day at most, and only when there is news. This also signs you up to our weekday newsletter, The LatAm Brief. Nothing arrives until you click the confirmation link, and you can stop either with one click. Privacy policy.
Why Banks Lend So Little
Ecoanalítica pointed first to the legal reserve requirement, known in Spanish as the encaje legal. It said the rule leaves about 73% of the deposits banks collect immobilised at the central bank, the Banco Central de Venezuela (BCV).
Money that cannot be lent cannot fund new loans, and the firm said this limits banks’ ability to multiply money. It described credit as being kept at marginal levels in the economy.
Penalties add to the squeeze. Ecoanalítica said the BCV raised the surcharge on a reserve shortfall from 48.8% to 144%.
Descifrado reported that the rules in force add penalties of up to 4 percentage points depending on how often a bank falls short, over periods of 8 to 30 days. Banca y Negocios confirmed that the BCV recently approved a larger penalty for reserve shortfalls, without giving the rate.
According to Ecoanalítica, those costs raise banks’ operating expenses and can push interest rates up. Higher lending rates make loans dearer for households and firms and can dampen demand for credit.
Business Leaders Make the Same Complaint
At the 82nd Annual Assembly of Fedecámaras, its president Felipe Capozzolo said Colombia and Brazil hold about 50% of GDP in loans, while Venezuela does not reach 4%. Finanzas Digital reported his remarks on Tuesday 13 October.
Capozzolo said the lack of financing leaves Venezuelan companies unable to expand, and he called for a lower reserve requirement. Fedecámaras is the country’s main private business federation, so its figure is an advocacy estimate rather than an official statistic.
The two figures differ in precision but point the same way, with Ecoanalítica at 3.4% and Fedecámaras at under 4%. Neither is a central-bank number.
A Loan Book That Is Growing From a Small Base
Banca y Negocios, a Caracas financial outlet, published a monthly bank ranking on Saturday 17 October based on a report by the advisory firm Aristimuño Herrera & Asociados. It put total bank loans at the end of September at the equivalent of US$4.25 billion at the official end-of-month exchange rate.
That was up 3.43% on August and 56.04% on a year earlier when measured in dollars. Measured in bolívares the portfolio grew 654.7% in a year, but the outlet noted that the official exchange rate itself moved by 383.67% over the same period.
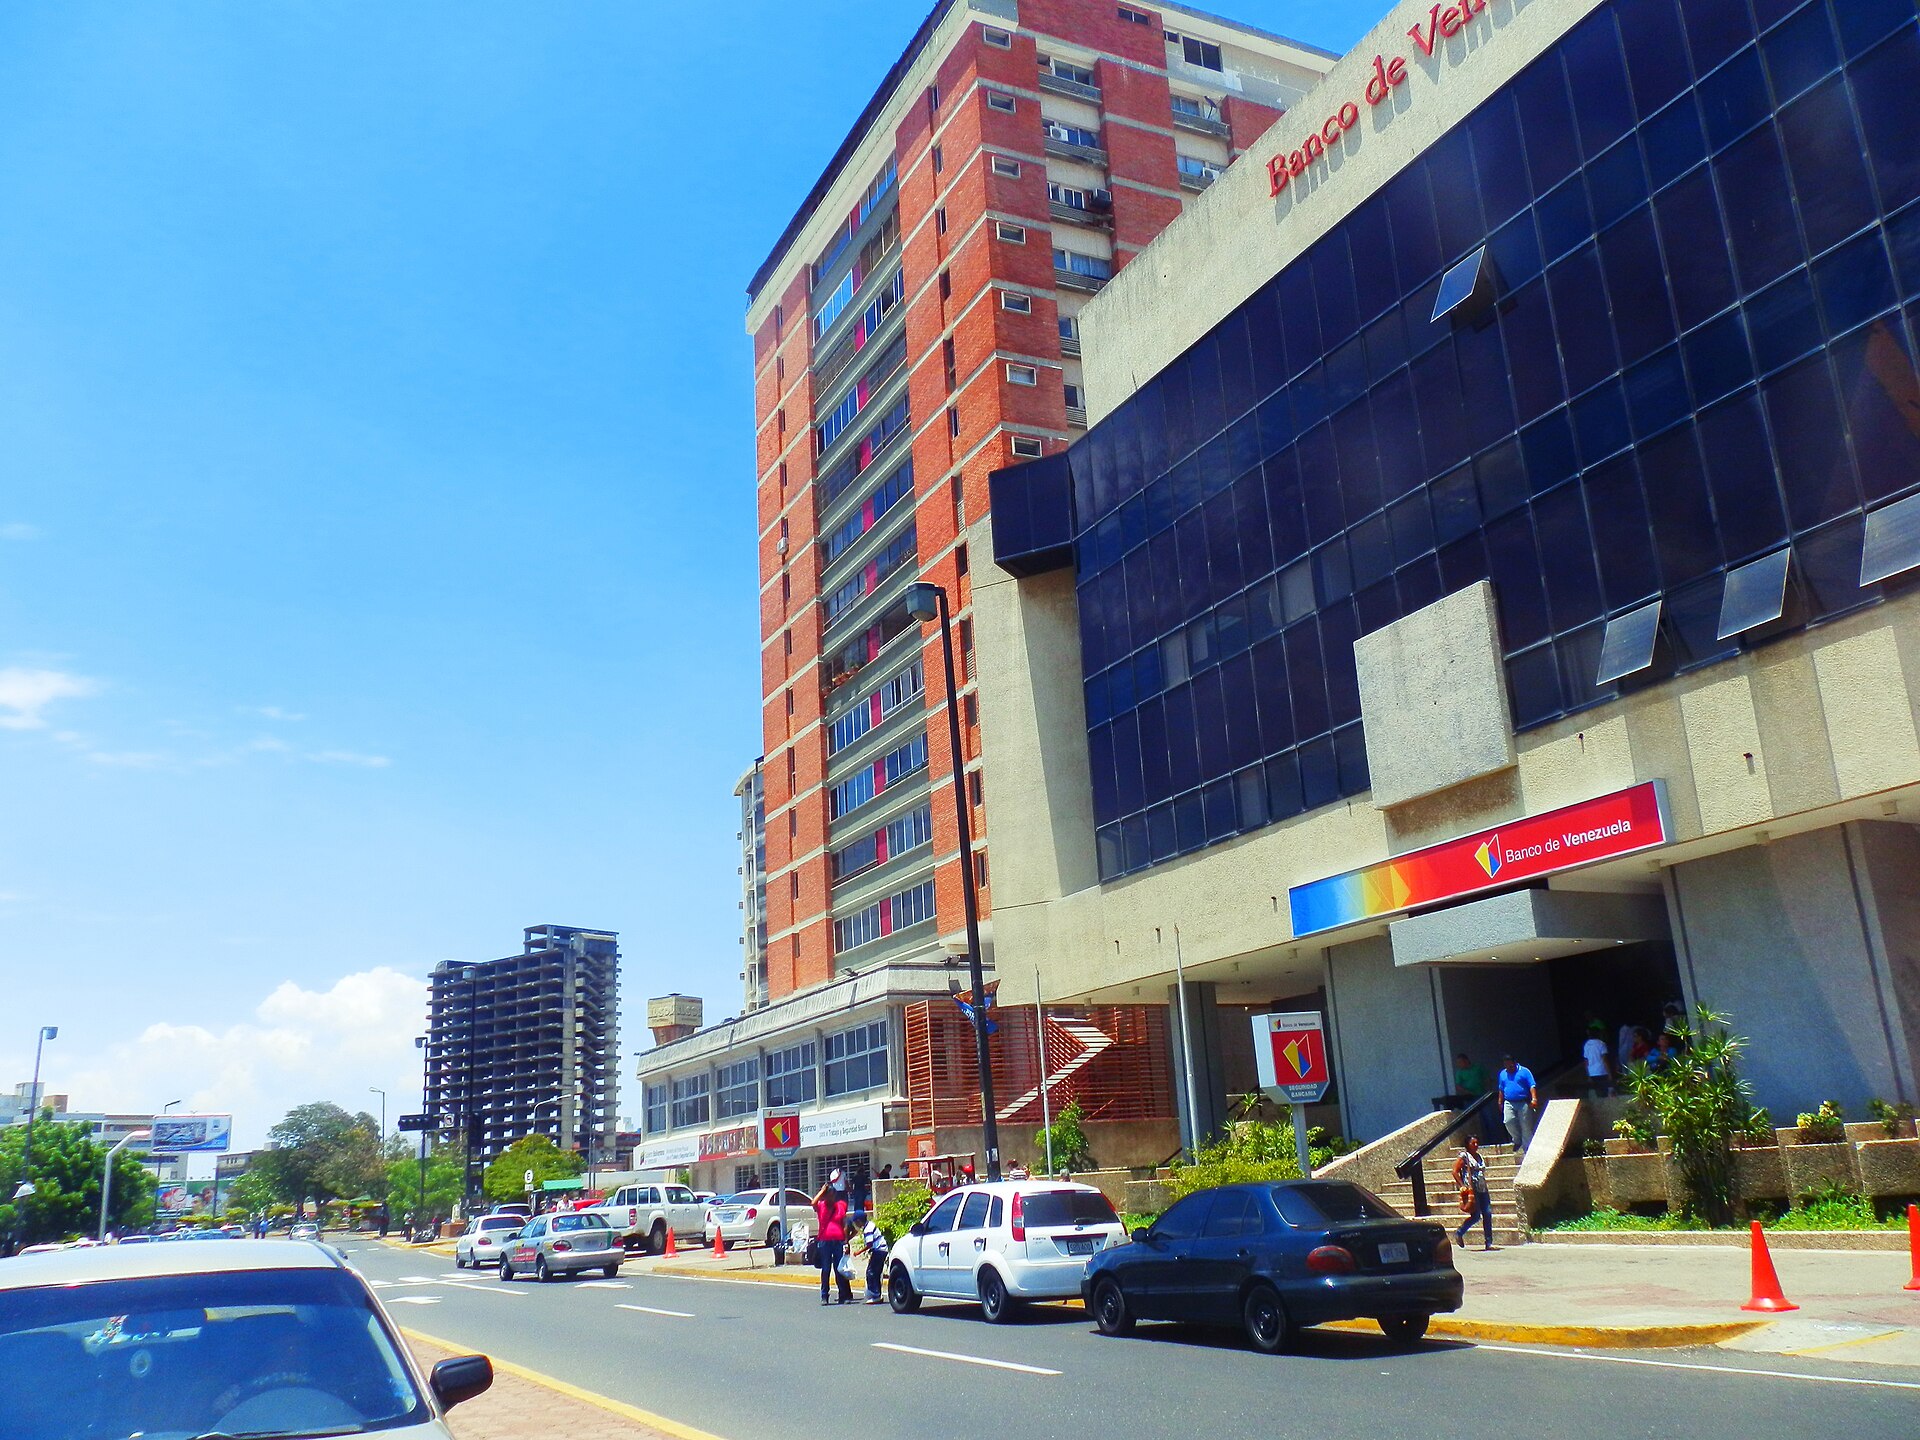
The same ranking reported a delinquency ratio of 1.02% in September, down from 1.08% in August and 1.39% a year earlier. State-owned Banco de Venezuela held 24.3% of the loan market and Banesco, the largest private bank, held 17.6%.
Those figures show lending is rising, but they do not contradict the low share of GDP. A book of about US$4.25 billion is small for an economy of Venezuela’s size, and the ranking itself said its September data did not yet reflect the newer interest-rate and reserve-penalty changes.
What Ecoanalítica Says Would Change It
Ecoanalítica tied any recovery of lending to structural reforms. It named three: bringing the reserve requirement closer to international standards, building sustainable interest-rate schemes, and letting banks lend directly against dollar deposits.
The firm said such steps could widen banks’ capacity to intermediate and improve access to financing for households and firms. Whether the BCV will move on any of them has not been announced in the coverage reviewed.
The wider backdrop includes disinflation, which we covered in Venezuela Inflation Slows to 8.4% in September, and the return of multilateral lenders. Our report Venezuela Welcomes IDB Back to Caracas, No Loans Yet described that earlier step.
What It Means for You
US companies, oil-service firms and exporters that sell into Venezuela should plan for little local working capital among their partners. Customers and partners there will often struggle to find bank financing for large orders.
For residents and visitors, thin lending can mean fewer consumer loans and less credit than in neighbouring countries. The sources reviewed do not describe everyday payment habits, so this is an inference from the low lending level.
Investors should treat the 3.4% level of Venezuela bank credit as a sign of both risk and room to grow. If the reserve rule eases, lending could expand quickly from a very low base, but nothing in the sources shows that decision has been taken.
What Is Not Known
Ecoanalítica’s original Instagram post could not be opened for this article, so the 3.4% figure rests on two Venezuelan outlets that quote it. The firm’s GDP basis, date and loan definition are not stated in either report.
It is not known whether the BCV will lower the 73% reserve rate or change the surcharge, and no official statement on the subject was found. The 73% rate and the surcharge figures are Ecoanalítica’s numbers as relayed by the two outlets and were not checked against a BCV circular.
No independent estimate of credit as a share of GDP was found to confirm 3.4%. The Fedecámaras figure of under 4% is consistent with it but comes from a business lobby.
Frequently Asked Questions
How much bank credit does Venezuela have compared with GDP?
Ecoanalítica puts it at 3.4% of GDP. Fedecámaras says it is below 4%.
Why do Venezuelan banks lend so little?
Ecoanalítica points to a legal reserve requirement of about 73% of deposits and to heavy surcharges for shortfalls. Those rules leave banks little money to lend.
How does Venezuela compare with Chile, Panama and Colombia?
Ecoanalítica lists Chile at 75.3% of GDP, Panama at 69.5% and Colombia at 46.1%. Venezuela at 3.4% is a small fraction of each.
Is bank lending in Venezuela growing?
Yes, from a low base. A monthly ranking put the loan book at about US$4.25 billion at the end of September, up 56.04% in a year in dollar terms.
What does it mean for US companies?
They should expect little local credit among Venezuelan partners. Banks may lend more if the central bank eases its reserve rules.
Sources: Descifrado, 17 October 2026; La Patilla, 17 October 2026; Finanzas Digital, 13 October 2026; Banca y Negocios, 17 October 2026; Ecoanalítica public posts as relayed by the outlets above.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error · Editorial responsibility: Matthias Camenzind, Editor-in-Chief
The Rio Times · Power Map
See who really holds power in Latin America
Click to open the Power Map →






 English (US) ·
 French (CA) ·
 French (FR) ·